GSV 150
The Most Transformational Growth Companies in Learning & Workforce Skills
Presented by

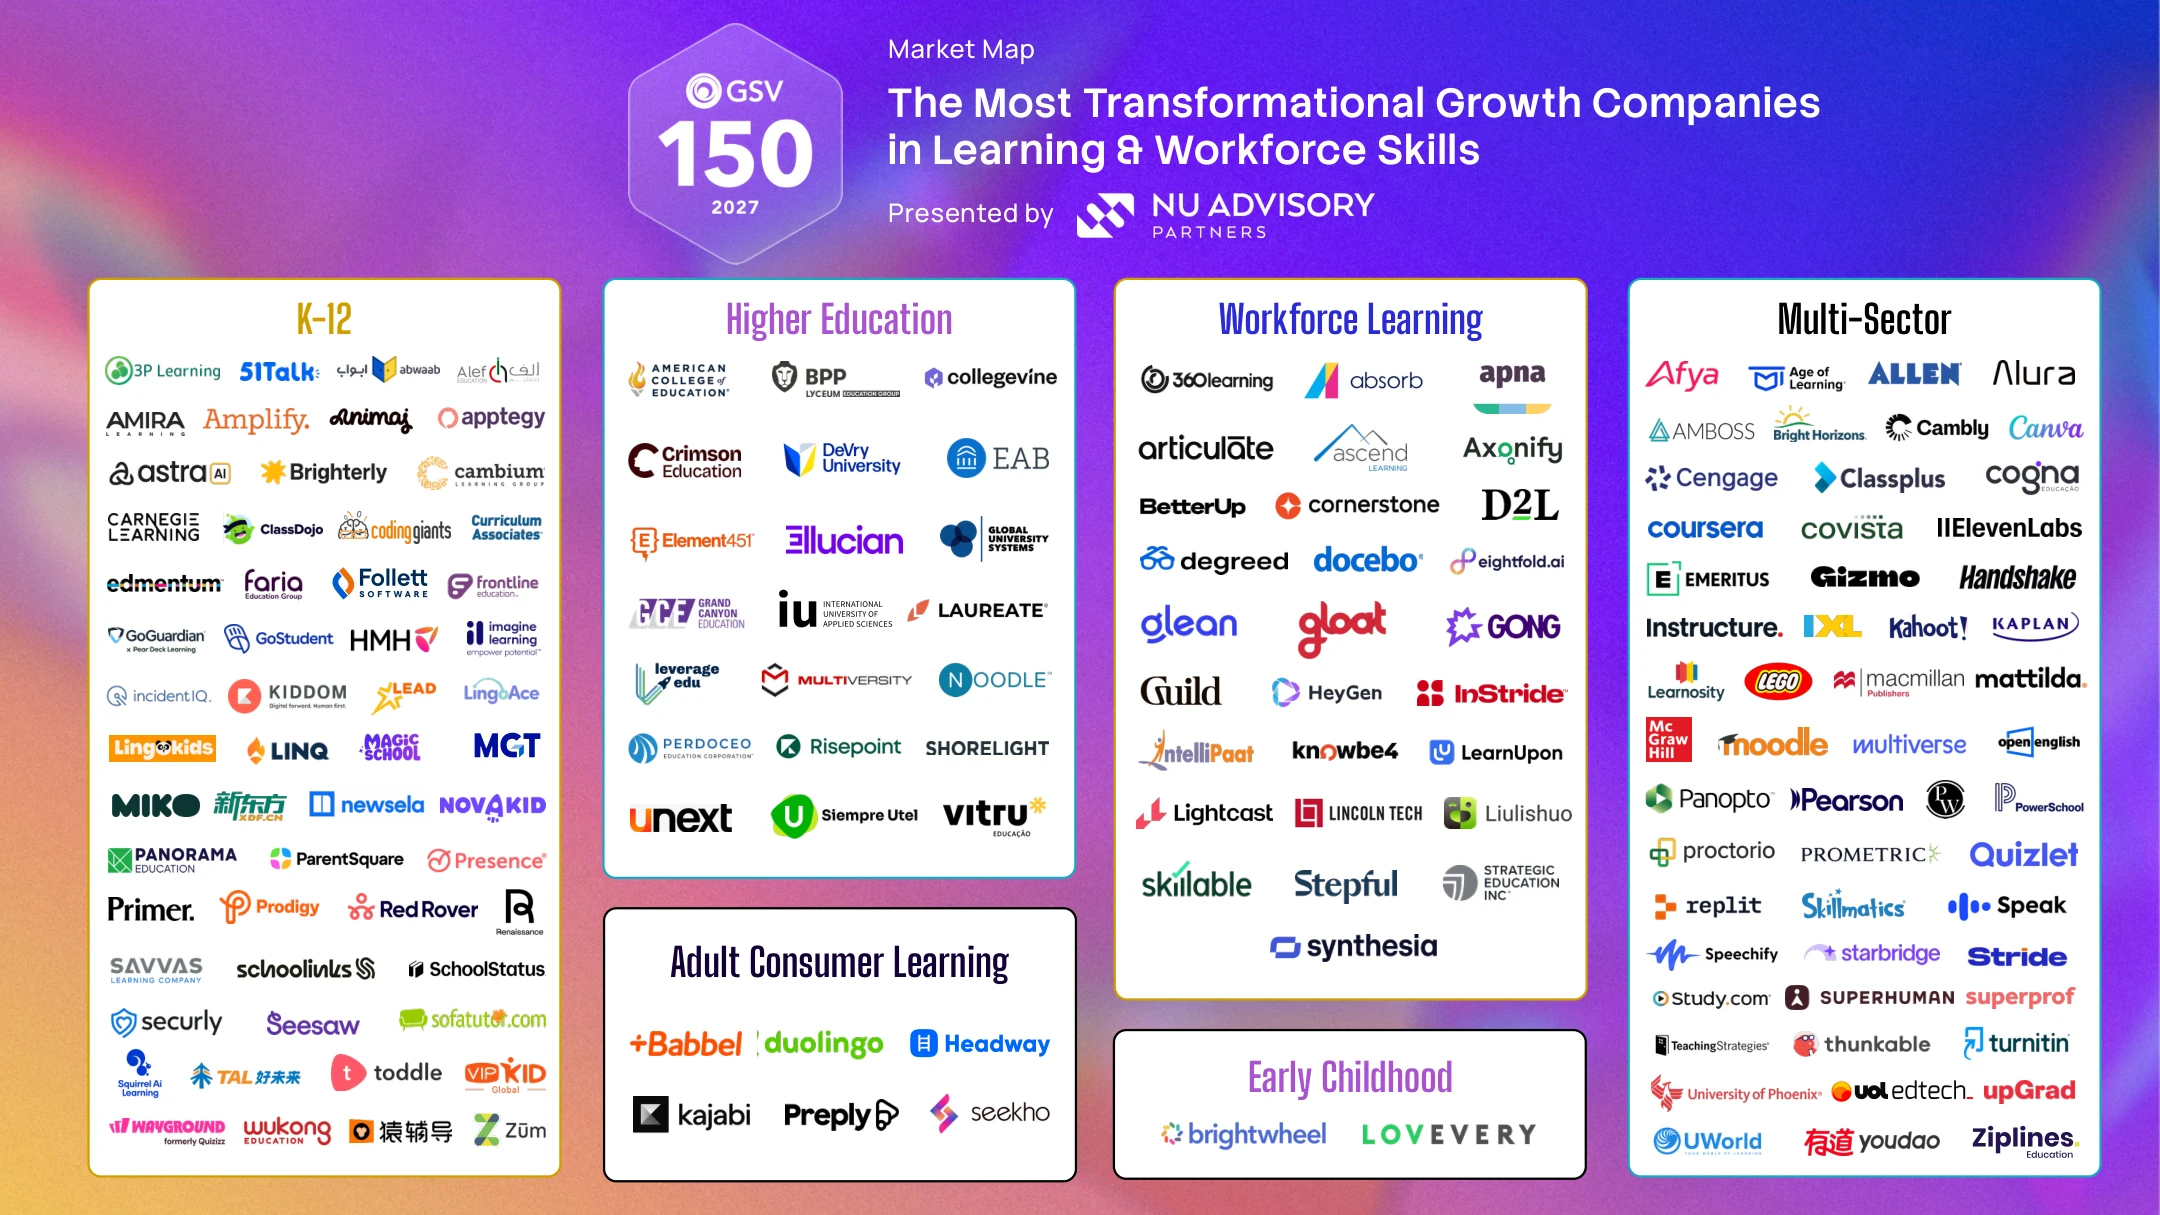
The 2027 GSV 150, presented by NU Advisory Partners, recognizes the world's most transformational growth companies in learning and workforce skills. At a time when the possibilities for learning and work are expanding rapidly, this year's GSV 150 celebrates category leaders turning innovation into meaningful opportunity, reaching new markets, and helping more people learn, grow, and thrive.
GSV evaluated leading global companies using a proprietary rubric across five factors: revenue scale, revenue growth, active learner reach, geographic footprint, and margin profile. The GSV 150 includes both public and private companies headquartered across 23 countries that collectively generate more than $50 billion in annual revenue, reflecting their scale and global reach.
With AI increasingly ubiquitous and often invisible across learning and work, companies built on AI continue to demonstrate extraordinary growth. This is evident in the hyper-growers on this year's GSV 150—companies above $50 million in revenue or ARR and growing their top line in the triple digits—including ElevenLabs, Glean, Handshake, HeyGen, MagicSchool, and Replit.
This year's GSV 150 also reveals a broader convergence of markets, capabilities, and business models. Companies are breaking down traditional boundaries and bringing together complementary capabilities to address the evolving needs of learners, educators, and employers. They are driving this shift through both product expansion and strategic acquisitions, with more than one in five GSV 150 companies completing or announcing acquisitions in 2026, totaling more than 50 deals across 34 companies. Several 2026 GSV 150 honorees, including Udemy, Workera, and Cursor, attracted strategic acquirers this year, a testament to the value they built.
By sector, 55% of this year's GSV 150 companies serve K–12, followed by 39% in workforce learning, 38% in higher education, 12% in adult consumer learning, and 4% in early childhood, with nearly a third spanning multiple “PreK to Gray” sectors. Geographically, North America leads (59% in the U.S. and 3% in Canada), with significant representation from Europe (15%), India (9%), and China (5%).
GSV evaluated leading global companies using a proprietary rubric across five factors: revenue scale, revenue growth, active learner reach, geographic footprint, and margin profile. The GSV 150 includes both public and private companies headquartered across 23 countries that collectively generate more than $50 billion in annual revenue, reflecting their scale and global reach.
With AI increasingly ubiquitous and often invisible across learning and work, companies built on AI continue to demonstrate extraordinary growth. This is evident in the hyper-growers on this year's GSV 150—companies above $50 million in revenue or ARR and growing their top line in the triple digits—including ElevenLabs, Glean, Handshake, HeyGen, MagicSchool, and Replit.
This year's GSV 150 also reveals a broader convergence of markets, capabilities, and business models. Companies are breaking down traditional boundaries and bringing together complementary capabilities to address the evolving needs of learners, educators, and employers. They are driving this shift through both product expansion and strategic acquisitions, with more than one in five GSV 150 companies completing or announcing acquisitions in 2026, totaling more than 50 deals across 34 companies. Several 2026 GSV 150 honorees, including Udemy, Workera, and Cursor, attracted strategic acquirers this year, a testament to the value they built.
By sector, 55% of this year's GSV 150 companies serve K–12, followed by 39% in workforce learning, 38% in higher education, 12% in adult consumer learning, and 4% in early childhood, with nearly a third spanning multiple “PreK to Gray” sectors. Geographically, North America leads (59% in the U.S. and 3% in Canada), with significant representation from Europe (15%), India (9%), and China (5%).
Featured
Thank you! Your submission has been received!
Oops! Something went wrong while submitting the form.